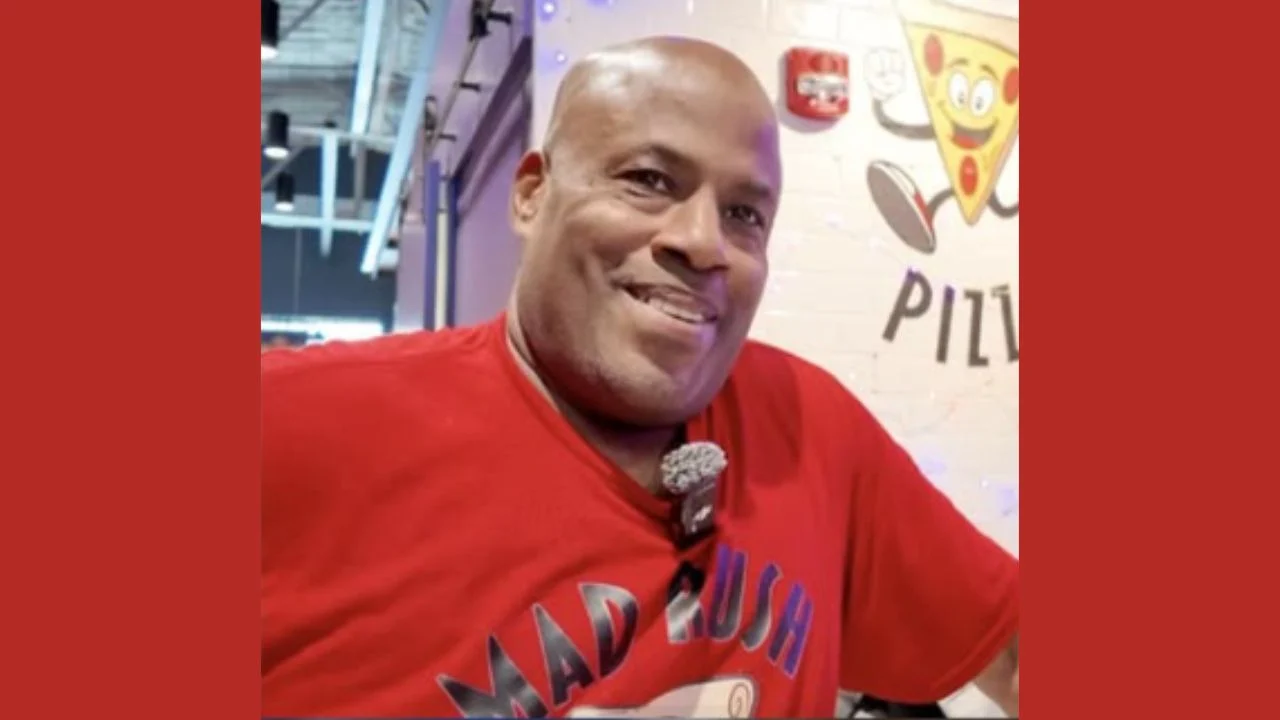
A Wisconsin pizza shop owner says a small-business loan scam cost him $9,000 and has left him fighting to keep the business he spent years building alive.
Laron Taylor owns Mad Rush Pizza at the Mequon Public Market, where he has operated his stall for about two and a half years. Taylor had been looking for financing for the shop when he handed over bank information as part of what he thought was a legitimate loan process.
The first week brought a problem he could not explain: a check was deposited for more than he had asked for. Taylor said the check was returned and more money was later withdrawn. He never got the $9,000 back.
Meanwhile, equipment bills at Mad Rush Pizza were mounting, and Taylor was paying for medication related to congestive heart failure. He has since started a fundraiser to keep the business going and is talking about the scam in hopes that another owner recognizes the setup before money leaves the account.
The Check Was for More Than Taylor Had Asked For
Taylor told TMJ4 that he knew something was off almost immediately. “I got suspicious in week one, when they deposited a check that was more than what I asked for, and then they returned it and then withdrew more money,” he said.
He had already given out his bank details. What Taylor thought would bring money into the business instead left him $9,000 behind, and he said attempts to recover it went nowhere. TMJ4 described what happened as an overpayment or “phantom loan” scam. The outlet did not identify the supposed lender or the people behind the offer, and Taylor did not name them in the interview.
“Everything came crashing down at once,” he said.
The Scam Wasn’t the Only Expense Taylor Was Trying to Cover
Taylor had spent about two and a half years building Mad Rush Pizza at the Mequon Public Market before losing the $9,000. Equipment was already eating into the shop’s money, with Taylor telling TMJ4 those costs had become harder to keep up with. His fundraiser says equipment failures added more bills after the scam in May.
There were personal expenses too. Taylor has congestive heart failure and pays for prescription medication while trying to cover the restaurant’s costs. His fundraiser says he spent the months after the scam trying to catch up, with the money being raised intended to help cover rent, payroll, equipment repairs or replacement and medication.
By September 15, the campaign had raised $2,000 of its $10,000 goal from 29 donations. Taylor said the people around the market have helped him keep going. “It’s a community here, and everybody is supportive,” he told TMJ4. “It just feels like I’m coming to do something I love to do, and I hope that can continue.”
The fundraiser says Mad Rush Pizza could close without enough support, but Taylor is hoping it does not come to that. “Everything will hopefully work out, and I’ll be able to stick around for a long time,” he said.
A Bank Can Show the Money Before It Knows the Check Is Fake
Seeing a deposit in an account can make a check look settled when it is not. The FTC says banks generally have to make deposited funds available quickly, while finding out that the check itself is fake can take much longer, sometimes weeks.
By then, the person who deposited it may have already sent money somewhere else. When the bank eventually rejects the check, it can take the deposited amount back out of the account, but money the customer already sent does not automatically come back.
A check for too much deserves attention before anything is returned. In a common overpayment scam, the sender comes up with a reason for the extra money and asks for the difference back. The FTC advises people not to send it. Taylor’s account included another problem: he had also supplied bank information during the supposed loan process and said money was withdrawn after the oversized check was returned.
If the Loan Looks Wrong, Check the Company Somewhere Else
A business owner looking for financing will normally be asked for financial information at some point. The FTC advises owners to research an unfamiliar financing company before sending bank details or other confidential records. If the offer arrived through an email, advertisement or unfamiliar website, the company can be checked without using the links or telephone numbers that came with the pitch.
Searching the lender’s name with words such as “scam” or “complaint” can turn up problems other borrowers have reported. If the company claims to represent a bank or established lender, contact information from that institution’s own website gives the borrower another way to check. The amount of any check should also match what was discussed, and there is no reason to return an unexpected difference while a payment is still being verified.
If bank details have already been shared and withdrawals start appearing, the financial institution should be contacted immediately. Account holders can ask what transactions can still be disputed and whether access to the account needs to be restricted or changed. Loan messages, check images, bank records and telephone numbers should also be kept rather than deleted once the deal falls apart.
Fake-check and small-business scams can be reported to the FTC at ReportFraud.ftc.gov.